Quick Answer
Tallahassee business owners can get commercial loans from four kinds of lenders:
- Hometown banks: Capital City Bank and Prime Meridian Bank
- Local credit unions: First Commerce, FSU Credit Union and Addition Financial (formerly Envision)
- National and super-regional banks: such as Truist, Wells Fargo, Bank of America, Chase and Synovus
- National SBA specialists: such as Live Oak Bank and Newtek
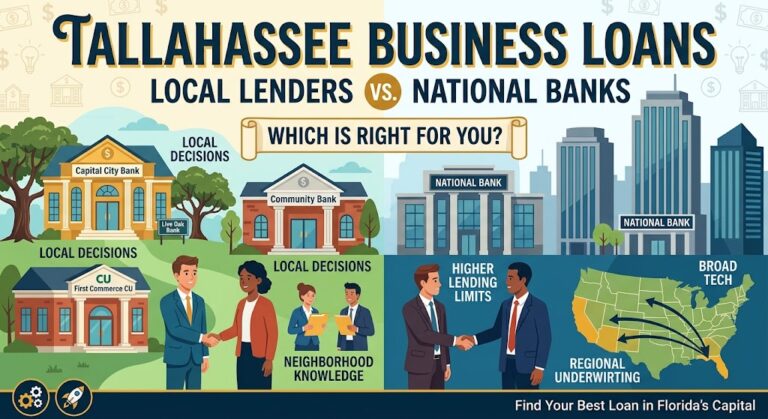
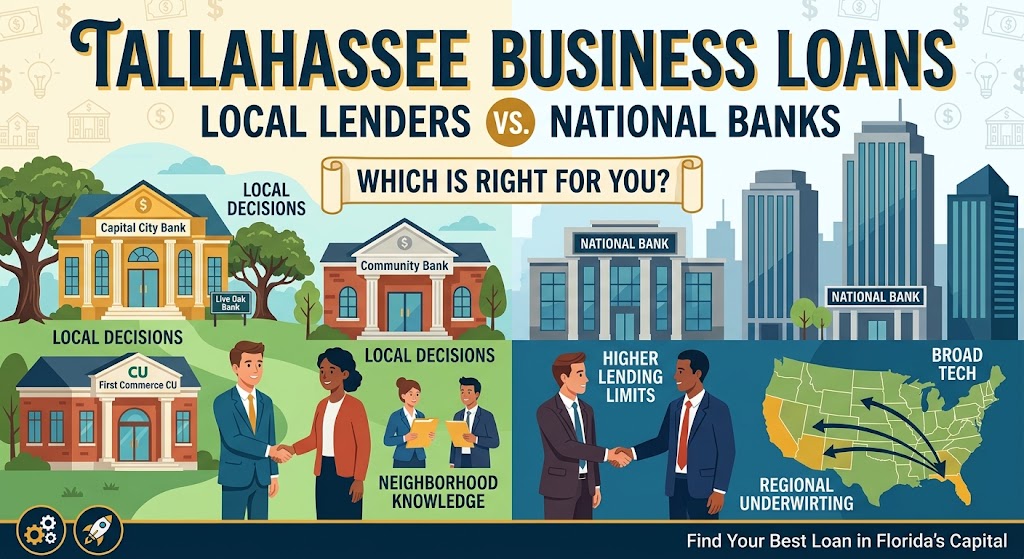
Local lenders usually offer faster, relationship-based decisions. National banks offer larger balance sheets and more treasury tools.
Who Lends to Businesses in Tallahassee
Hometown Commercial Banks
Capital City Bank is the capital’s legacy institution. It was founded in 1895 and is still headquartered in Tallahassee. It offers business term loans, commercial real estate financing, owner-occupied property loans, construction loans and treasury management. The bank has also been adding business bankers in Leon County. In May 2026 it announced a commercial lender with more than 20 years of Tallahassee experience.
Prime Meridian Bank was founded in 2008 and is based in Tallahassee. It has offices in Tallahassee, Crawfordville and Lakeland. Its loans include commercial real estate, equipment, construction, business lines of credit and both SBA 7(a) and 504 financing. It reported roughly $975 million in assets in early 2025, which puts it among the larger community banks based in North Florida.
Local Credit Unions
First Commerce Credit Union calls itself Tallahassee’s largest local credit union. It runs 14 financial centers across North Florida and South Georgia. It lends for operating expenses, equipment, inventory and commercial real estate, and it offers business checking up through full treasury services.
FSU Credit Union offers business banking alongside its consumer products. It has several Tallahassee branches, including Capital Circle NE and West Tennessee Street.
Addition Financial Credit Union absorbed Tallahassee-based Envision Credit Union in October 2025. The combined institution has more than $3.8 billion in assets, over 250,000 members and 37 branches in Florida and Georgia. Former Envision members now bank with Addition Financial, which is headquartered in Lake Mary.
National and Super-Regional Banks
Large banks with Tallahassee branches bring higher lending limits and more sophisticated cash management. They also offer multi-state banking for companies with operations outside North Florida. The tradeoff is that larger credit decisions often go to regional underwriting teams rather than a local loan committee.
National SBA Specialists
Many SBA loans to Tallahassee firms come from lenders with no local branch. In fiscal 2025, Live Oak Bank was the nation’s top SBA 7(a) lender at about $2.8 billion, and Newtek Bank was second at over $2 billion. These lenders work online and focus on business acquisitions, franchises and professional practices.
Local vs. National Lenders at a Glance
| Factor | Local Banks & Credit Unions | National Banks |
|---|---|---|
| Decision-making | Often local loan committee | Often regional underwriting |
| Turnaround | Typically faster on mid-size deals | Faster on standardized small loans |
| Relationship | Banker knows local market | Varies; more product-driven |
| Loan size | Lower legal lending limits | High capacity for large deals |
| Treasury tools | Solid, fewer specialty products | Broadest cash management suites |
| SBA programs | Many participate; check PLP status | Most large banks are SBA lenders |
| Fees | Often lower, more negotiable | More standardized fee schedules |
| Membership | Credit unions require membership | Open to any qualified business |
Why Credit Union Business Loans Have a Ceiling
Credit unions face a federal cap that banks don’t. The total of a credit union’s member business loans generally can’t exceed the lesser of 1.75 times its net worth or 1.75 times the net worth needed to be “well capitalized.” In practice, that usually works out to about 12.25% of total assets.
For borrowers, this cap rarely matters on a $250,000 equipment loan. It can matter on a multimillion-dollar commercial real estate project. That’s when a credit union may bring in participation partners, or a bank may be the better fit. Loans fully secured by a 1- to 4-family dwelling don’t count toward the cap.
SBA Loans: The Most Common Route for Small Firms
SBA-guaranteed loans are often the easiest path for Tallahassee businesses with limited collateral or a short operating history. Nationally, SBA guaranteed about 84,400 7(a) and 504 loans worth $44.8 billion in fiscal 2025.
Before applying, know these two programs:
- SBA 7(a): general-purpose financing up to $5 million for working capital, equipment, acquisitions and real estate.
- SBA 504: long-term, fixed-rate financing for owner-occupied real estate and major equipment. A bank provides the first mortgage and a Certified Development Company provides the second.
Ask any lender whether it holds SBA Preferred Lender (PLP) status. PLP lenders can approve loans in-house. With a non-PLP lender, SBA does its own underwriting review, and that typically takes 60 to 90 days.
Local Help Before You Apply
The Tallahassee-Leon County Office of Economic Vitality (OEV) helps businesses find capital, choose sites and use incentives such as the Targeted Business Program. OEV also runs one of Florida’s largest Minority, Women and Small Business Enterprise (MWSBE) certification programs. Certification can open up City and County procurement opportunities that strengthen a loan application. OEV can be reached at (850) 219-1060.
The Florida SBDC at Florida A&M University offers free business plan reviews, financial projections and lender-readiness coaching. Those are the documents commercial loan officers ask for first.
How to Choose the Right Lender
- Size the deal first. Under $1 million, local banks and credit unions compete hard. Above $5 million, national or super-regional banks are usually needed.
- Match lender to loan type. Use community banks for owner-occupied real estate, SBA specialists for business acquisitions and credit unions for equipment and vehicles.
- Ask who makes the decision. A local loan committee can weigh context that a scoring model can’t.
- Compare total cost, not just rate. Ask about origination fees, prepayment penalties, deposit requirements and annual renewal fees on credit lines.
- Check SBA status. Ask whether the lender is a PLP if an SBA guarantee is likely.
- Expect a deposit relationship. Most commercial lenders require or reward moving your operating accounts to them.
Frequently Asked Questions
Where can I get a small business loan in Tallahassee?
Options include hometown banks (Capital City Bank, Prime Meridian Bank), local credit unions (First Commerce, FSU Credit Union, Addition Financial), national banks with Tallahassee branches, and online SBA lenders such as Live Oak Bank and Newtek.
What are the best business banks in Tallahassee?
It depends on deal size. Capital City Bank and Prime Meridian Bank are the main Tallahassee-headquartered commercial banks. First Commerce is the largest local credit union. National banks fit companies that need large credit facilities or multi-state treasury services.
Do I need a local business bank account to qualify for Leon County economic development programs?
Generally, no. OEV incentives and MWSBE certification depend on factors like business location, licensing, ownership, job creation and investment, not on where you bank. Confirm the terms of any specific program with OEV directly.
Is Envision Credit Union still in Tallahassee?
Envision merged into Addition Financial Credit Union on October 1, 2025. Former Envision members and branches now operate under the Addition Financial name.
Can a credit union make a large commercial real estate loan?
Yes, within limits. Federal rules cap a credit union’s total business lending at about 1.75 times its net worth. Large projects may need loan participations or a bank partner.
How long does a business loan take in Tallahassee?
Conventional loans from local lenders often close within several weeks once documents are complete. SBA loans move faster with Preferred Lenders. Non-PLP SBA loans commonly take 60 to 90 days.
Sources and Further Reading
- Capital City Bank Group, “Capital City Bank Expands Tallahassee Presence with Business Banker Willie Correa,” press release, May 13, 2026
- Capital City Bank, Tallahassee Commercial Real Estate Loans and branch services pages
- FDIC, Community Reinvestment Act Performance Evaluation: Prime Meridian Bank, September 30, 2024
- DepositAccounts, Prime Meridian Bank institution profile (Q1 2025 financials)
- MarketBeat, Prime Meridian Holding Company company profile
- First Commerce Credit Union, Locations and Business Real Estate Loans pages
- Candid/GuideStar, First Commerce Credit Union organization profile
- Greater Tallahassee Chamber of Commerce, Credit Unions member directory
- Tyfone, “Members approve merger between Addition Financial and Envision credit unions,” 2025
- Addition Financial Credit Union, “Addition Financial Credit Union and Envision Credit Union Announce Intent to Merge,” December 17, 2024
- Code of Federal Regulations, 12 CFR § 723.8, Aggregate member business loan limit
- NCUA Examiner’s Guide, Aggregate MBL Limit
- CUNA (America’s Credit Unions), Member Business Lending
- Coleman Report, “Top 100 SBA 7(a) Lenders by Loan Amount FY25,” November 17, 2025
- U.S. Small Business Administration, News Release 25-83, fiscal year 2025 lending results, September 30, 2025
- Greater Tallahassee Chamber of Commerce, Local Incentives
- Leon County, Tallahassee-Leon County Office of Economic Vitality resource listing
- IEDC, “The Collaboration of Economic Development Organizations” webinar materials (OEV MWSBE program)
About the Author